● REPLAY ACTIVE | 12-MINUTE STRATEGY MASTERCLASS
KEEP YOUR LOW RATE.
BUY YOUR NEXT HOME.
1-on-1 Scenario Modeling • 100% Confidential • No Obligation
THE HOMEOWNER'S DILEMMA
You secured a historic 3% mortgage rate years ago, and on paper, staying put looks like the only rational financial move. But in reality, your life has evolved. Your family has outgrown the floor plan, your daily priorities have shifted, and the home you live in no longer reflects the lifestyle or legacy you are building.
A lot of homeowners feel stuck because they don’t want to give up their low interest rate.
So they stay in a home that no longer fits their life even when they’re ready for something different.
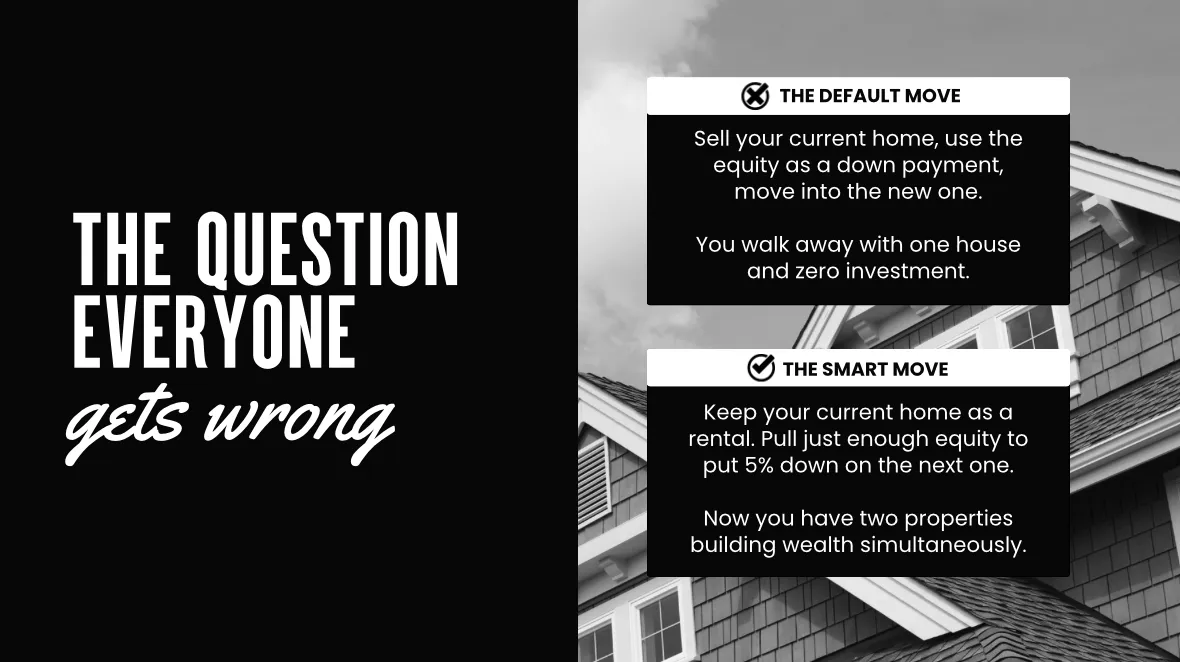
But what if moving didn’t mean giving up the rate you already have?
SAMPLE DUAL-ASSET SIMULATION
REAL-WORLD MODEL
Hypothetical illustration of converting a starter home into a performing rental while acquiring a long-term primary residence.
COMBINED ASSET VALUE
$1.15M
Total baseline portfolio valuation that could be retained simultaneously across both properties.
EST. MONTHLY CASH FLOW
+$850
Projected net rental surplus that may help offset new primary housing payment obligations.
5-YR PRINCIPAL PAYDOWN
$72K
Debt reduction that could be funded entirely by tenant rent payments over a 60-month horizon.
EST. 10-YR WEALTH GAIN
$340K+
Compound equity and appreciation potential that may be realized across two appreciating properties.
MODEL ASSUMPTIONS & DISCLOSURE: Figures shown represent a mathematical model based on hypothetical 3.8% annual property appreciation, conservative rental occupancy, and structured amortization. Individual results may vary based on market conditions, property equity, tenant terms, and mortgage structure. This is an educational model and not a commitment to lend.
CONFIDENTIAL ANALYSIS
Every scenario is personally audited by Chris Kloc or his team. We do not operate a call center, nor is your financial data distributed to third-party lenders or marketing aggregators.
- 100% Private, Direct Modeling: No junior analysts or third parties
- No Hard Credit Inquiry Required for Preliminary Analysis
- Customized Mathematical Comparison Delivered Within 24-48 Hours
Your asset details remain confidential under strict institutional compliance standards.
STRATEGIC INQUIRIES
TRANSPARENCY & CLARITY
Before you make any decisions, we’ll run the numbers.
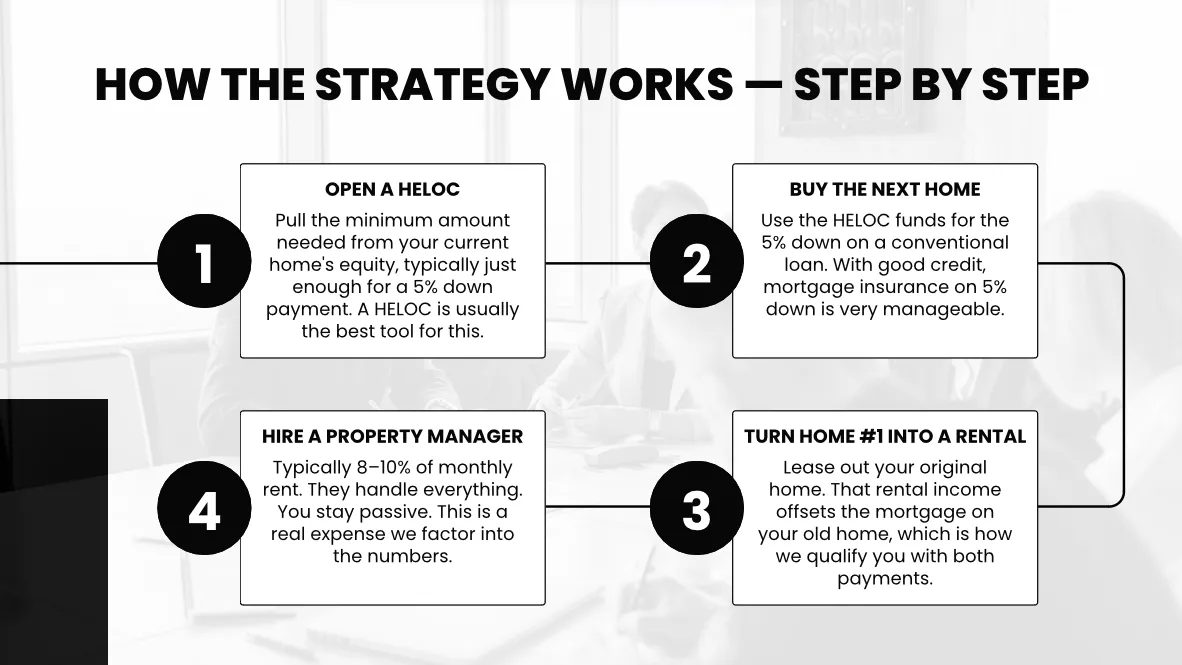
We’ll look at your current home, your equity, your mortgage, and the home you want to buy to see what the strategy could actually look like for you.
How do I purchase my next property without selling my current home first?
You may not have to sell your current home before buying your next one.
Depending on your situation, you may be able to use some of the equity in your current home or potential rental income from it to help you qualify for your next home.
That means you could keep your current home, keep your low rate, and still make a strong offer on the home you want.
Doesn't giving up my 3% interest rate destroy long-term wealth?
That’s exactly why this strategy is designed to help you keep it.
Instead of replacing your current low-rate mortgage, you may be able to keep that home and that rate while buying your next home.
And if you keep both properties, you now have two homes potentially building equity over time instead of one.
The key is looking at the whole financial picture, not just the interest rate on the new home.
What happens if market rates drop after we structure my new mortgage?
If rates come down later, we can look at refinancing your new mortgage.
The goal is to build a plan that works for you at today’s rates, while still giving you the ability to take advantage of lower rates in the future.
You don’t have to wait for the perfect rate to start looking at your options.